A real estate analyst recently wrote that “In the real estate industry especially, buy and hold investment approaches are in essence simple spread businesses. Spread means the difference between rental yields (in our example we took gross rental yield based on in place rents) and the cost of interest-bearing debt (CoD).”
This vision of real estate is as far as reality as one can be, and ignores that running a (permanent) real estate business is much more an operational task than a financial gimmick.
Ignoring the physical reality of a real estate asset (it is depreciating over time, and need much care an attention), is a proven recipe for disaster, and had led not so long ago to a substantial amount of tears.
Our approach to real estate is for and foremost operational. Our underwriting of real estate is unlevered, in order not to cloud our judgment with cheap debt, and easy money. alstria will benefit from the low interest rate environment in the future, and the implied increased carry on our assets. However, this is done on assets which have an intrinsic value, beyond the cheap cost of funding. This value is underpinned by business plan that rely on reasonable market assumption, and more importantly on the ability to implement this business plans. Not on the biggest fool theory.
This approach has allowed us to increase our FFO per share systematically over the last 5 years, and allows us yet again to guide to an increase for the year to come. Achieving this result was possible thanks to a strong investment in our real estate operations, the dedication of our people to operation of the assets and the emphasis we put on our sticking to our strict underwriting criteria. We see no reason to change this approach, as we believe this is the only sustainable way forward. Carry trade in real estate is a dead wrong approach.
Showing posts with label real estate. Show all posts
Jan 16, 2015
Dead wrong
Labels:
accounting,
carry,
governance,
Hamburg,
IFRS,
interest rates,
investment,
real estate,
trade,
yields
Oct 25, 2014
The #GRESB Conundrum
We have been asked by a number of investor the reason why we have decided not to submit our data to GRESB this year (the data itself is available on our website www.alstria.com/sustainability ).
In order to better explain our position we have used the following presentation.
We are obviously happy to discuss, so please feel free to send us feedback.
In order to better explain our position we have used the following presentation.
We are obviously happy to discuss, so please feel free to send us feedback.
Labels:
building,
CSR,
environment,
green,
green buildings,
GRESB,
investor,
IR,
real estate,
reit,
relation,
responsible,
sustainability
Jun 11, 2014
This time it is different
It has been a while since I have not written anything on alstria’s blog. I started from time to time, but never get to finish the work. This morning however, when I read the piece about the German real estate, that was featured in the daily newsletter of Property Investor Europe (which is usually the first think I read in the morning), I knew I would get through.
The “Expert view”, which is
called “Upward trend on
the German commercial real estate market” (and available here: http://aox.ag/PIE_German_office
) gives an overview about why investors should be investing in the German
office sector, which per see, should not lead to any specific comments from my
side. Except that, when I finish reading the post, I suddenly felt younger by 7
to 8 years. If you want a list of all the bad reasons to invest in the German
office market, this post is definitely the right place to start. It is making 5
assumptions that should lead a decision to invest in German office space.
Assumption 1: Economic
growth in Germany is resulting in increasing demand for office space
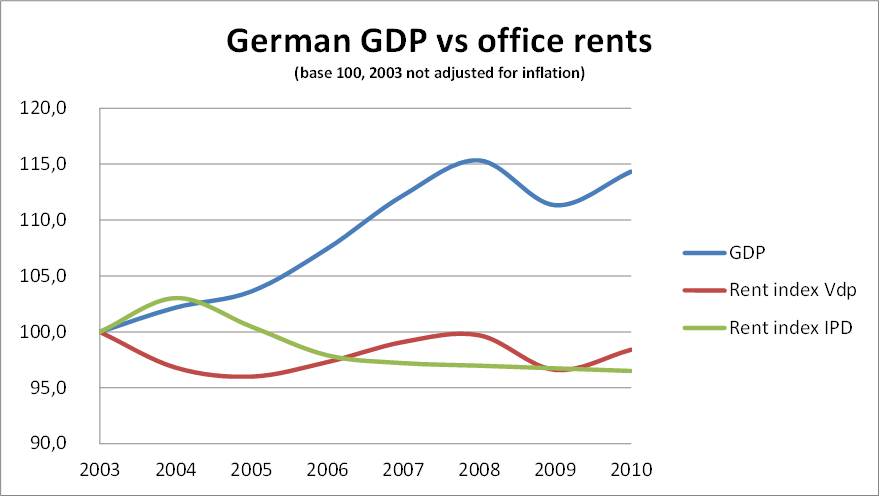
This is a graph that was
published on this blog four years ago (and would lead to the same result if
extended to 2014).
I am amazed to see that
some commentators are still arguing about the fact the GDP growth correlate with
office rental growth. This might have been the case 30 years ago, but it is
clearly not the case anymore. The way tenants are learning to optimize their
office space, and the efficiency gain they are realizing are by far outstripping
any additional need of space created by GDP growth. Do not expect any substantial
rental growth in the German office sector, nor substantial vacancy reduction. It is unlikely to happen anytime soon.
Assumption 2: Financing of
commercial real estate is becoming cheaper
That is absolutely true.
Financing is cheap. I would have thought that I would never again hear this as
an argument for buying real estate (nota: alstria always underwrite assets
based on unlevered returns), but apparently I was wrong.
Assumption 3: Rising
demand for office premises with a positive impact on rental markets
See point one above. This has
never happened in the past, and I see no reason why it will happen in the
future. Absorption in the market is at best neutral, more realistically negative.
Assumption 4: Ongoing
investment pressure is driving transaction volumes and is reducing risk
aversion
The first part of the assessment is
absolutely correct, investment volume is going up, and has accelerated drastically
over the last weeks (mainly on long term leased assets, driven by yield
seekers). But I am not sure that risk aversion is reducing. Short term leased
assets, or other assets with potential operational risk/leverage are not so
much in demand. Not sure though that the risk aversion is reducing, but clearly
the risk return profile of some of the assets which are being considered for
trading is deteriorating.
So what is the German office market all about then ?
Obviously we all have our views
on the market and how it is going to develop, and mine is as good as any other.
The fact of the matter is that our position is based on an educated guess, not a crystal ball. We
believe that the German office market is going to be driven by operational excellence,
vs. financial engineering. That real estate needs more operators and less
financial sponsors. that driving returns should come from increased market share, better scaling of costs, operational excellence, better services to the clients (some call them tenants). That expectation of market rental growth driven by macro factors, should not be considered, and will only enhance returns if its happens.
In my last roadshow meeting, when
I was discussing the state of the investment market and the increased
transaction volume we are seeing in Germany, I was asked by an investor if I felt
any similarity with 2006-2007. My answer at this point was that I did not, as I
believed most of the players in the market still have the deep scares and bad memories
of what happened then. I think it is Mark Twain who once said "History does not repeat itself, but it does rhyme". Well PIE this morning was rhyming very strongly with 2007 (and if in doubt here are the same arguments put together in 2007:
At that time DB concluded as follow:
"The greatest risk in the years ahead therefore lies not in a downswing on the property markets, but in exorbitant expections on the part of investors and project developers"
I guess this last point is still up-to-date
Labels:
alstria,
capital,
crisis,
equity,
europe,
german,
germany,
increase,
investment,
investor,
real,
real estate,
reit,
transactions,
valuation
Jan 8, 2013
Socially Responsible Investment
What if one equity research firm
was to send to a company it covers a questionnaire asking specifically for
nonpublic information. This would be done in order to provide its clients with
a “more accurate picture” of the company that what is achievable through public
disclosure. How would the company react? And how would the compliance
department of the research firm react?
You think no one would do that?
Think again. It is done every year for a significant number of companies among
the most respected one. It is done every year by research firm that publish
report about the Corporate Social Responsibility (CSR) of issuers. It is to a
certain extend ironic that these questionnaires will all circle around
corporate governance and compliance issues. In order to fill them, you need to
break one basic rule of corporate governance: Equal treatment of shareholders.
I realized this was the case,
following changes at the GRESB (www.GRESB.com),
a real estate CSR benchmarking non-profit group. We have been submitting data to the GRESB for
the last two years (Our latest answers can be found here http://aox.ag/UzTCzV). What I, and probably a
number of other companies initially overlooked, is that the GRESB is not only a
benchmarking tool. In actual fact the data we would submit to GRESB would be
re-used by GRESB, and fed into (paid?) research, that would be provided to
selected investors.
My first reaction was to write
the GRESB management a letter explaining that I did not felt that this was
appropriate. However, before drafting such a letter I have done some research
about how other do it. The most prominent of theses research firm (as they
provide the research for Footsie4Good) is EIRIS (www.EIRIS.org).
Much to my surprise, they actually openly and specifically mention that they
would ask companies for non-public information. The headline on the company
survey page reads as follow: “The EIRIS
survey is a way for us to get the information that our clients require that
is not already publicly available.” http://www.eiris.org/companies/eiris_survey.html
You might argue that this kind of
information is not relevant for the investment decision. However, it seems
important enough for AXA, BlackRock, and a number of other high profile
investor to pay to get access to this information. It is also interesting to
see that this information will then be available (against payment) on websites
like www.CSRhub.com
Another high profile CSR adviser SAM (which deal with the Dow Jones sustainability index) is less explicit about the nature of the information it asks companies to report on. The website mentions that : "The annual assessment is based on an online questionnaire supported by extensive company documentation" http://www.sam-group.com/en/sustainability-insight/sam-corporate-sustainability-assessment.jsp
Anyway, this does not
seem to have been caught up by any regulator, which tends to demonstrate that
non-financial information is not considered as critical by regulators.
From today on, alstria will
publish on its website the full extent of the questionnaire that we fill up to
these kind of research firms, in order to make sure everyone have access to the
same level of information. I will also still ask GRESB what their position on
the topic is. It might as well be that I have it all wrong.
Labels:
CSR,
EIRIS,
GRESB,
insider,
real estate,
shareholders,
SRI,
sustainability,
trading,
transparency
Dec 21, 2012
Life Insurance
The say on the street is that
there is a funding gap in the European property market. The say is also that
new players are coming along to fill, or benefit from this gap. These new
players are called debt funds, or insurance companies. Reports are piling up
announcing the raise of new funds, or the billions that this or this insurance
company is planning to invest in the new yield Eldorado. Advisors are warning
about banking regulation risks looming on the new sector, and offering advice… And
journalist have been writing about it (for instance here http://aox.ag/12tjxdn, here http://aox.ag/12tjw9c and here http://aox.ag/TbXMdh )
I have been wondering how much of
all of this is actually for real, and how much is there to help us sleep at
night. The white knights are coming to save our industry from its own cliff.
The fact is that there are a
number of high profile loans which have been put together by insurance
companies (not so much by funds so far). The Deutsche Bank and the Silber
Towers in Frankfurt, some prime assets in London… So there is some action going
in there. But is that really new? In the syndicated facility of alstria back in
2007 we also had AXA as part of the consortium with one of its debt fund
(alongside with 25 banks). Today we do have a fund from Deka as part of our
banking syndicate.
We also hear that unlike in the
US, insurance companies have never really be involved in the financing of real
estate in Europe. This is not exactly true. The lion share of the Pfandbrief
bonds (the German cover bond market which finance real estate across Europe)
are actually sold to insurance companies (although we could not identify any statistic
in that respect). According to the Vdp, the total amount of Pfandbrief loan
outstanding in Europe at the end of 2011 was around EUR 297 billion. The
pfandbrief banks granted EUR 90 billion of new real estate loan in 2011. This
compares with, for instance, Allianz target of EUR 5 billion loan book by 2015 (
http://aox.ag/UhbZHW )or the total EUR 2
billion of new loans by insurance companies in 2011…
From my perspective, the key
question in this debate is not really whether or not insurance companies will
step in the lending business. But are they going to do this with new capital,
or is the lending business just part of the existing real estate allocation. GE
Real Estate for instance (which I appreciate is not an insurance company, see
here http://aox.ag/T3EytC ) is stepping out
of equity, and coming back into debt. Net net, the move is neutral… No new
capital.
Labels:
allianz,
covered bond,
debt,
equity,
europe,
insurance,
life,
pfandbrief,
real estate,
reit
Nov 20, 2012
Adding the numbers

A short mathematical problem for my eight years old son to solve:
· At 30/09/2011, the total NAV (Net Asset Value)of the German open ended funds was 85.151 mEUR.
Assuming that over the period the asset value is only influenced by net flows, can you calculate how much theses in(out)flows are ?
Here is my son’s answer (and any other kid for that matter):The total flow for the period is equal 83.173 – 85.151 = - 1.979. Given that this number is negative, this is an OUTFLOW.
You think this is obvious. Well it is not. At least not for the Bundesverband Deutscher Investment-Gesellschaften or BVI. For the German Funds Association which states that “it enforces improvements for fund-investors and promotes equal treatment for all investors in the financial markets. BVI`s investor education programs support students and citizens to improve their financial knowledge”, the simple math above do not work.
According to the BVI the correct answer to the question above is a net INFLOW of EUR 2.766 mEUR. In other words 83.173– 85.151 = +2.766…
This is not an isolated mistake. If you look for the BVI net inflow publications for real estate open ended funds from 2007 to 2011 theses are the numbers you will dig out:
While “NET inflow” for the period was around EUR 13.7 b, the total NAV of the funds grew by a little less than a 10th of that. How does this work?
In order to understand the forces at work, you need to take a look at the same set of numbers, published this time by the Deustche-Bundesbank. The Bundesbank publishes two additional numbers. One is the total outflow, and the second one is the total distribution paid. The Bundesbank also make it crystal clear that the NET-inflow numbers disregard any distribution.
The previous table looks like this in the Bundesbank report:

With this additional information the numbers make sense (the reason why the numbers do not add-up exactly is because of the underlying performance of the funds which impacts the NAV). The so called Net Inflow, is for the most of it, not more than a dividend re-investment scheme. It has NO influence whatsoever on the amount of money available to invest in real estate.
The information which is has been provided by the BVI to the market for years is highly misleading. The vast majority of the market participants believe that the net inflow which is publish is what it name says it is: Net inflow, ie. new money that is coming into real estate. Here are a couple of example of some investors/advisors that have been across the years willingly or not mislead by the BVI communication.
Google will provide you with dozens of other examples. Since the publication of the last BVI figures last week, I have received at least 5 daily emails of investment banks mentioning the fact that open-ended funds had EUR 2,7 b of inflow year to date. All of them were hinting to the fact that this money will need to be invested (at least partly), therefore driving demand. This is just not the case. In actual fact, the total amount of money available for investment in real estate went DOWN.
The BVI recently published an analysis where it found that there are significant deficiencies in the corporate governance of German listed companies. That might as well be true. But assuming the BVI really cares about the topic, I would strongly encourage them to start cracking at their own issues first.
NB: all the numbers quoted in this post are sources from:
http://www.bundesbank.de/Navigation/EN/Publications/Statistical_supplements/statistical_supplements.html (supplement 2 as of 28/09/2012)
May 23, 2012
Green Lanterns
IPD has started an interesting
new index in the French market, called the IPD Green Real estate index. It
basically analyses the performance of Green buildings and compares it with both
recent non-green buildings as well as with the general IPD index (http://aox.ag/KdpWzJ)
As far as I know, this is the
first time such an indicator is put together. This is more than welcome
initiative as it might once and for all stop the rhetorical debate about whether
or not Green adds value to the asset.
On the face of it, it looks as if
it does add value. Total return last year for the green building stood at 7,4%.
That is 1,1% higher than equivalent non green building which showed a total
return of 6,3%. However devil is in the details.
Here is how this performance is
broken up:
The green building performance is
solely driven by a (theoretical?) capital value improvement. It relative
performance is very poor in turns of Income Returns with assets yielding around
2% less than the rest of the market. More interestingly the IPD data reveal that
there is no rent difference between Green and non-green buildings (average ERV
is at 356 EUR/sqm/year for non-green vs 361 EUR/sqm/year for green building).
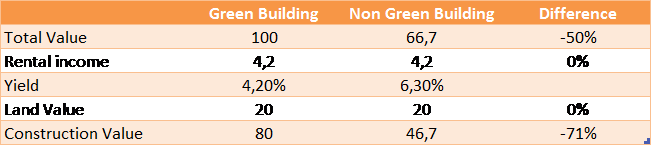
These data allow for an interesting
(theoretical) analysis about the benefit of investing in the green building. Let’s
assume a green office building which is worth 100. According to IPD data, this
asset will generate around 4,2 of rent. Let’s now assume a non-green building
asset generating the same rent. According to IPD this asset is yield 6,3% ie.
is worth 66,7. From there you can derive the actual value as described in the
following table.
As a result of the IPD data, you
can determine in a few minutes that the market offers a 71% premium for the
value of a “Green” construction over a non-green construction. At this stage it become clear what you want to build if you are a developper. The only economical explanation for such a premium would be that a green building will depreciate much slower than a non-green
building. It would therefore deserve a premium as it would deliver returns on a longuer period of time.
The table below, summarizes the
number of years needed to collect enough rent in order to pay for the
construction cost at a given unlevered expected return (the NPV of the cash
flow is equal to zero).
What the previous table show is that If you expect a 5% return from a non green building, assumes no terminal value, no rental growth, no capex... you need to collect the rent for 16 full years. For a green building for which a 71% premium was paid, you need to collect rent for 54 years. Another way to say this is that the premium reflect the belief that the green building life will be 3,3 times longuer than the non green building.
So now, here is the question:
Which assets do you think is going to generate the most sustainable returns
over time? I am not going to take position. However I have lost faith long ago
in Hal Jordan and the believe that “Green is the color of will”
Labels:
DGNB,
green buildings,
IPD,
listed companies,
market,
MIS-LEED-ING,
real estate,
reit,
sustainability,
transparency
Apr 17, 2012
Point of view
Following the publication of our
latest annual reports we had a number of discussions with some analysts and
investors (as we did last year for that matter) with respect to the write-off
in value that we have published on our short leased assets.
We usually argue that from our
perspective we would offer a lower price for a vacant building than we would
for the same asset with a one year lease, which in turn should be cheaper than
the same building with a two years lease … We always felt it makes a lot of
sense to reflect this into our valuation process, and thus devalue every year
the short dated assets to reflect the shorter lease term.
A recent article published by
property magazine international (http://aox.ag/Ii71mp)
is bringing a new perspective to the subject, based on a recent IPD analysis (this is the IPD Press release http://aox.ag/HVdOBX).
According to IPD (as quoted by
the article), UK landlords who give tenants five years leases immediately wipe
out almost 2% of the value of their building.
Quote: “IPD lease length analysis shows
that signing a new five year lease leads to a fall in value of around -1.8%,
despite the property being let.”
Let’s all take a deep breath and
step back for a minute to look closer to what IPS is suggesting here? If I read
this correctly, the valuation of building which have signed a new five year
lease (so which obviously were vacant or closed to be vacant) have LOST value
because of the new lease. In other word, if investors would have paid 100 for a
vacant building, they would only pay 98 for the same building with a five year
lease. In essence, you would be better off keeping the asset vacant, rather
than signing a short term lease. I don’t know about you, but this does not pass
my smell test.
I might have a very twisted mind,
but I would like to suggest another explanation for the whole story. What if
the initial valuation of the building was wrong? What if the asset was never
worth 100 in the first place? What if the new lease has shown beyond dispute
that the assumption to get to the 100 value cannot be hold on to? Can it be
that if the building was initially worth only 90 or 95, then the 5 year lease
did increase the value to 98?
From where I stand, in 99% of the
cases, a cash flow producing asset is going to be worth more than the same
asset vacant. Regardless of the length of the cash-flow. As such, we do devalue
our assets when they are close of becoming vacant and we do show an increase in
value when leases are renewed.
Where do you stand?
Labels:
IPD,
real,
real estate,
rent,
rental growt,
valuation
Apr 10, 2012
To go please !
I have been trying to figure out
how to improve the utility management process of the company for quite a while
now. This topic is important for us for a number of reasons, and I am deeply
convinced that we need to find the right way to address this while time is
still on our side. Not only managing utilities is the main way to improve
sustainability credential of an asset, but utilities represent the bulk of our
tenant costs. Any extra cents going to utility providers is a cent that we cannot
use to increase the rent. On a longer timeframe consideration, I do believe
that the future of leasing will be (as it is already in some Nordic countries)
in the full service rent were utility costs will be borne by the real estate
owner, rather than by the tenant.
One of the bigger hurdles
commercial real estate is going through with respect to improved utility
management is in my view the “short” average ownership/management continuity
that drives of industry. As I have argued before, real estate time is much
slower than capital market time. Short ownership for a real estate is in my
view anything between 5 to 7 years. Most of the investment that would be needed
in order to measure and understand what is going on with a building would have
a longer payout period. Without such measurement, and understanding, there is
little you can do. More importantly, it is very unlikely that any buyer of the
asset would pay for this specific piece of technology. The likelihood that a
new owner system would be compatible with yours is very close to zero. The
result is that most real estate owners underinvest into modern tools that would
allow a better grasp on utility bills of building, as they will not capture
enough benefit of the investment over its holding period. I am still confused, that
I am able to know instantly that Lady Gaga changed its dress (@ladygaga on
Twitter), our buildings are not able to communicate real time data. Not that
the technology is lacking, but the cost of the technology is prohibitive within
our potential ownership timeframe.
What we would need is a
technology that would allow us to plug something into an existing metering
system, and then be in position to take that something away with us whenever we
would sell the asset to someone else. This would ease the investment decision,
as the lifetime of the investment would not be tied up to a single asset but to
the “plug and play” device itself. The good news is that there are a bunch of
start-up companies out there that are developing just that. It is early
development stage, lot of progress to be made, but definitively going into the
right direction. We will be looking into that closely to see if it can really
work. Monitoring “to go”, is what we really need.
Labels:
alstria,
DGNB,
office,
real estate,
real time,
sustainability
May 6, 2011
Nash Equilibrium
A number of open ended funds are offering their unit holders a very nice opportunity to make good usage of game theory and figure out what to do next. Some funds (see related article in the Immobilien Zeitung -in German- http://aox.ag/lvAZK1 ), are asking their current unit holders, what would be their behavior if the funds were to reopen for redemption. The underlying idea, is that the more unit holders opt for redemption, the more likely is the fund to liquidate.
Labels:
equilibrium,
game,
germany,
Germany. Open Ended Funds,
nash,
real estate,
theory
Dec 9, 2010
Japanese’s whispers
I have put on a paper some thoughts while I was in roadshow in Asia, following meeting with investors and investment analysts. As a disclaimer, I am writing this in the middle of a jetlagged night, and I clearly do not pretend to know what I am talking about here.
1- In China, it seems that it is more reasonable to invest into less known secondary cities, than in the majors. Rational being that a lot of speculation is driven by some cities names, not by economics. Ring a bell in Germany as well. Except that Frankfurt is by no way a major city by Chinese standards
Labels:
Asia,
frankfurt,
real estate,
reit,
rental growt
Nov 12, 2010
Hold your fire
We had the question on alstria’s quaterly call this week. Listening to other German real estate companies call, and reading a number of analyst note, it seems that there is a growing number of (non German) market participant who expect “distressed sales” coming from the German open ended funds (mainly of the ones which said they will liquidate).
Is German open ended funds liquidation a great buying opportunity for real estate investor? The answer, is probably no. Or at least not yet.The fund managers have three years to sell their assets. Therefore, they expect that the liquidation is going to be done in an orderly manner, with little “distress” attached to it, and they might as well be right.
Oct 28, 2010
Little Dorrit
Anyone interested in real estate investment is aware of the „difficult“ times the German open ended fund industry is going through. As you can expect the German press is full of article trying to figure out what happened, what a solution would be (may I naively suggest listing?) and whether or not it is safe to invest in them again.
Labels:
Dicken,
germany,
Germany. Open Ended Funds,
investment,
real estate,
transparency,
valuation
Aug 18, 2010
Honi soit qui mal y pense
In the foreword to a green supplement in the magazine House and Garden (in 2008), the Prince wrote: "Why, I must ask, does being 'green' mean building with glass and steel and concrete and then adding wind turbines, solar panels, water heaters, sedum roofs, glass atria - all the paraphernalia of a new 'green building industry' - to offset buildings that are inefficient in the first place?
"That many of these add-ons are mere gestures, at best, is now clear, as their impacts on home energy consumption can now be measured and usually offer scant justification for the radical nature of the design." (see http://bit.ly/bjibZy for more on this)
Labels:
green buildings,
real estate,
reit,
RICS,
sustainability
Jul 8, 2010
We (almost) made it happen
News that I felt went through pretty much un-noticed in the last month was the publication of the latest Jones Lang LaSalle transparency index (you can register for free on JLL website and download the study here). For the first time since inception, the German market is part of the “tier 1” countries, along side with the UK, Australia, France and 12 other countries. More precisely Germany is quotes by JLL as the 10th more transparent market among the 81 markets covered by the study, and 6th more transparent among the 34 European market surveyed.
Labels:
germany,
real estate,
reit,
transparency
Apr 22, 2010
Ginger Ale
The CMBS market is back. At least so they say. An article in the FT (which can be read here), suggests that a first 350 M€ CMBS was placed in the Netherland. That is real news, as the stall of the CMBS market is clearly one of the main concern still out there. It is becoming mainstream wisdom that there is a large debt overhang coming up, which is to a great part linked to CMBS.
The bizarre part of the press release was linked to the fact that the "CMBS" was rated AAA by all the rating agencies. This looks bizarre as usual CMBS are (use to be) made of different tranches with different rating. I was interested in getting a better understanding of the placement and went to the website of the issuer to see if i could gather additional details (the full press release is available here). And I did. The main information being that this deal was placed as one tranche to a single investor... Being able to place EUR 350 million of debt in the current market IS an acheivment per say, however, not enough to claim that the CMBS market have reopenned.
Labels:
CMBS,
debt,
germany,
rating,
real estate
Mar 12, 2010
CETERIS PARIBUS
alstria as a real estate company is very much interested in the debate relating Green Buildings and the better understanding of the fundamental of this new key development is an important factor in setting up the future strategy of the company. As part of background research work, I read recently a report called “Doing well by doing Good? Green Office Buildings”. It can be freely accessed following this link.
According to the study, it provides “the first credible evidence on the economic value of the certification of “green buildings”. The release of this report had a great impact and was widely commented by the real estate press (thus my willingness to read the study directly). You might have heard that Green Buildings command a 6% premium on rents and 16% premium on sale price. Well, this is where theses numbers come from.
Labels:
green buildings,
LEED,
MIS-LEED-ING,
real estate,
sustainability
Nov 9, 2009
Quality rather than quantity
The debate about the need for more transparency in the real estate listed sector is back in the Germany. In principle there is nothing bad about the requirement for more transparency. I hope that alstria has in the past demonstrated many times its willingness to provide the market with the right set of information at the right time. There is in my opinion a dangerous amalgam between transparency and throwing unsorted information to investors. I make a big difference between being transparent and publishing each and every data available in a company. Being transparent is not equivalent to ticking each box of a list of information that needs to be published by a company. Transparency is a dynamic and subjective notion. It is about disclosing the right information at the right time and in a way that is understandable by an investor. It is a judgment call.
Sep 4, 2009
Will Aristote save the real estate finance?
In the last 12 months we had numerous questions of investors on what is the Pfandbrief market (the German cover bond market) and how does this market works. I happened to run into an academic study that is a good introduction to the instrument. It is published on the web site of the VdP (Association of German Pfandbrief Banks). The study is dated February 2009, and is called “Refinancing Real Estate Loans – Lessons to be Learned from the Subprime Crisis” (full study can be downloaded following this link).
Labels:
CMBS,
covered bond,
debt,
finance,
germany,
real estate
Jun 12, 2009
Back to the Future

Michael J. Fox driving his DeLorean back and forth in the past and in the future, riding his skateboard, listening to Huey Lewis and the News singing the “Power of Love” was one of my favorite movies. I spent an awful lot of time looking at the VHS video (for those who are younger than 25, VHS tapes were big black boxes with movies of bad quality which you could watch on TV, and TVs at that time were also large boxes with a small screens).
Labels:
future,
germany,
real estate,
RICS,
valuation
Subscribe to:
Posts (Atom)