We have been asked by a number of investor the reason why we have decided not to submit our data to GRESB this year (the data itself is available on our website www.alstria.com/sustainability ).
In order to better explain our position we have used the following presentation.
We are obviously happy to discuss, so please feel free to send us feedback.
Showing posts with label reit. Show all posts
Showing posts with label reit. Show all posts
Oct 25, 2014


Jun 11, 2014
This time it is different

It has been a while since I have not written anything on alstria’s blog. I started from time to time, but never get to finish the work. This morning however, when I read the piece about the German real estate, that was featured in the daily newsletter of Property Investor Europe (which is usually the first think I read in the morning), I knew I would get through.
The “Expert view”, which is
called “Upward trend on
the German commercial real estate market” (and available here: http://aox.ag/PIE_German_office
) gives an overview about why investors should be investing in the German
office sector, which per see, should not lead to any specific comments from my
side. Except that, when I finish reading the post, I suddenly felt younger by 7
to 8 years. If you want a list of all the bad reasons to invest in the German
office market, this post is definitely the right place to start. It is making 5
assumptions that should lead a decision to invest in German office space.
Assumption 1: Economic
growth in Germany is resulting in increasing demand for office space
This is a graph that was
published on this blog four years ago (and would lead to the same result if
extended to 2014). 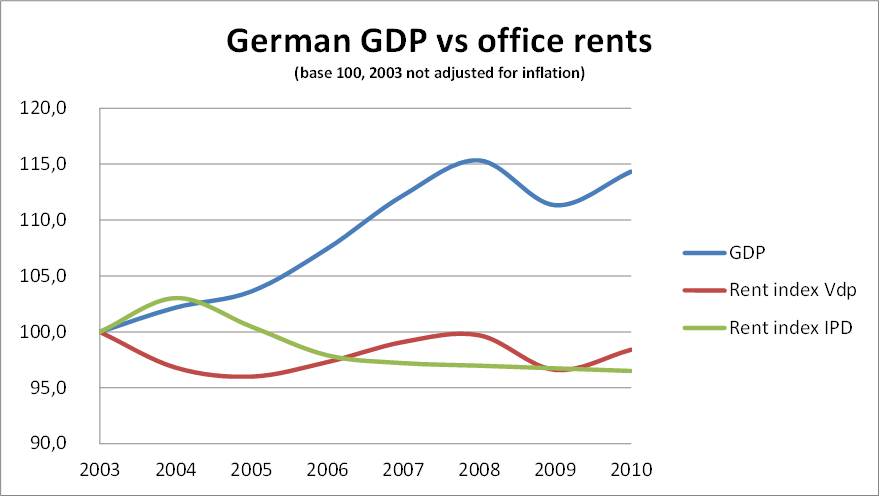

I am amazed to see that
some commentators are still arguing about the fact the GDP growth correlate with
office rental growth. This might have been the case 30 years ago, but it is
clearly not the case anymore. The way tenants are learning to optimize their
office space, and the efficiency gain they are realizing are by far outstripping
any additional need of space created by GDP growth. Do not expect any substantial
rental growth in the German office sector, nor substantial vacancy reduction. It is unlikely to happen anytime soon.
Assumption 2: Financing of
commercial real estate is becoming cheaper
That is absolutely true.
Financing is cheap. I would have thought that I would never again hear this as
an argument for buying real estate (nota: alstria always underwrite assets
based on unlevered returns), but apparently I was wrong.
Assumption 3: Rising
demand for office premises with a positive impact on rental markets
See point one above. This has
never happened in the past, and I see no reason why it will happen in the
future. Absorption in the market is at best neutral, more realistically negative.
Assumption 4: Ongoing
investment pressure is driving transaction volumes and is reducing risk
aversion
The first part of the assessment is
absolutely correct, investment volume is going up, and has accelerated drastically
over the last weeks (mainly on long term leased assets, driven by yield
seekers). But I am not sure that risk aversion is reducing. Short term leased
assets, or other assets with potential operational risk/leverage are not so
much in demand. Not sure though that the risk aversion is reducing, but clearly
the risk return profile of some of the assets which are being considered for
trading is deteriorating.
So what is the German office market all about then ?
Obviously we all have our views
on the market and how it is going to develop, and mine is as good as any other.
The fact of the matter is that our position is based on an educated guess, not a crystal ball. We
believe that the German office market is going to be driven by operational excellence,
vs. financial engineering. That real estate needs more operators and less
financial sponsors. that driving returns should come from increased market share, better scaling of costs, operational excellence, better services to the clients (some call them tenants). That expectation of market rental growth driven by macro factors, should not be considered, and will only enhance returns if its happens.
In my last roadshow meeting, when
I was discussing the state of the investment market and the increased
transaction volume we are seeing in Germany, I was asked by an investor if I felt
any similarity with 2006-2007. My answer at this point was that I did not, as I
believed most of the players in the market still have the deep scares and bad memories
of what happened then. I think it is Mark Twain who once said "History does not repeat itself, but it does rhyme". Well PIE this morning was rhyming very strongly with 2007 (and if in doubt here are the same arguments put together in 2007:
At that time DB concluded as follow:
"The greatest risk in the years ahead therefore lies not in a downswing on the property markets, but in exorbitant expections on the part of investors and project developers"
I guess this last point is still up-to-date
Dec 21, 2012
Life Insurance

The say on the street is that
there is a funding gap in the European property market. The say is also that
new players are coming along to fill, or benefit from this gap. These new
players are called debt funds, or insurance companies. Reports are piling up
announcing the raise of new funds, or the billions that this or this insurance
company is planning to invest in the new yield Eldorado. Advisors are warning
about banking regulation risks looming on the new sector, and offering advice… And
journalist have been writing about it (for instance here http://aox.ag/12tjxdn, here http://aox.ag/12tjw9c and here http://aox.ag/TbXMdh )
I have been wondering how much of
all of this is actually for real, and how much is there to help us sleep at
night. The white knights are coming to save our industry from its own cliff.
The fact is that there are a
number of high profile loans which have been put together by insurance
companies (not so much by funds so far). The Deutsche Bank and the Silber
Towers in Frankfurt, some prime assets in London… So there is some action going
in there. But is that really new? In the syndicated facility of alstria back in
2007 we also had AXA as part of the consortium with one of its debt fund
(alongside with 25 banks). Today we do have a fund from Deka as part of our
banking syndicate.
We also hear that unlike in the
US, insurance companies have never really be involved in the financing of real
estate in Europe. This is not exactly true. The lion share of the Pfandbrief
bonds (the German cover bond market which finance real estate across Europe)
are actually sold to insurance companies (although we could not identify any statistic
in that respect). According to the Vdp, the total amount of Pfandbrief loan
outstanding in Europe at the end of 2011 was around EUR 297 billion. The
pfandbrief banks granted EUR 90 billion of new real estate loan in 2011. This
compares with, for instance, Allianz target of EUR 5 billion loan book by 2015 (
http://aox.ag/UhbZHW )or the total EUR 2
billion of new loans by insurance companies in 2011…
From my perspective, the key
question in this debate is not really whether or not insurance companies will
step in the lending business. But are they going to do this with new capital,
or is the lending business just part of the existing real estate allocation. GE
Real Estate for instance (which I appreciate is not an insurance company, see
here http://aox.ag/T3EytC ) is stepping out
of equity, and coming back into debt. Net net, the move is neutral… No new
capital.
May 23, 2012
Green Lanterns

IPD has started an interesting
new index in the French market, called the IPD Green Real estate index. It
basically analyses the performance of Green buildings and compares it with both
recent non-green buildings as well as with the general IPD index (http://aox.ag/KdpWzJ)
As far as I know, this is the
first time such an indicator is put together. This is more than welcome
initiative as it might once and for all stop the rhetorical debate about whether
or not Green adds value to the asset.
On the face of it, it looks as if
it does add value. Total return last year for the green building stood at 7,4%.
That is 1,1% higher than equivalent non green building which showed a total
return of 6,3%. However devil is in the details.
Here is how this performance is
broken up:

The green building performance is
solely driven by a (theoretical?) capital value improvement. It relative
performance is very poor in turns of Income Returns with assets yielding around
2% less than the rest of the market. More interestingly the IPD data reveal that
there is no rent difference between Green and non-green buildings (average ERV
is at 356 EUR/sqm/year for non-green vs 361 EUR/sqm/year for green building).
These data allow for an interesting
(theoretical) analysis about the benefit of investing in the green building. Let’s
assume a green office building which is worth 100. According to IPD data, this
asset will generate around 4,2 of rent. Let’s now assume a non-green building
asset generating the same rent. According to IPD this asset is yield 6,3% ie.
is worth 66,7. From there you can derive the actual value as described in the
following table.
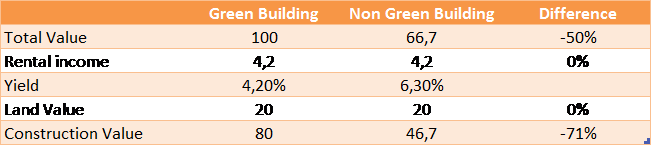
As a result of the IPD data, you
can determine in a few minutes that the market offers a 71% premium for the
value of a “Green” construction over a non-green construction. At this stage it become clear what you want to build if you are a developper. The only economical explanation for such a premium would be that a green building will depreciate much slower than a non-green
building. It would therefore deserve a premium as it would deliver returns on a longuer period of time.
The table below, summarizes the
number of years needed to collect enough rent in order to pay for the
construction cost at a given unlevered expected return (the NPV of the cash
flow is equal to zero).

What the previous table show is that If you expect a 5% return from a non green building, assumes no terminal value, no rental growth, no capex... you need to collect the rent for 16 full years. For a green building for which a 71% premium was paid, you need to collect rent for 54 years. Another way to say this is that the premium reflect the belief that the green building life will be 3,3 times longuer than the non green building.
So now, here is the question:
Which assets do you think is going to generate the most sustainable returns
over time? I am not going to take position. However I have lost faith long ago
in Hal Jordan and the believe that “Green is the color of will”
Apr 20, 2012
Forward looking statement
An interesting white paper published
recently by Collier International went un-noticed, while I believe it deserve
some attention and reading by anyone who is interested in the European office
market.
The white paper is the third
issue of a series called “Generation Y: Space planning and the future of
workplace design”. Below this (un)inspiring title lies an interesting tentative
calculation of the future demand for space in Europe (full document: http://aox.ag/Jyf8cg)
Collier equation is quite simple.
They consider office workers population trend considering population growth,
and remote working trends, as well as new workspace design trends, and add up
the numbers.
The result of this analysis for
an office hosting 200 employee in 2012 is summarized in the table below:

The methodology used by Colliers
can clearly be questioned. It is rather simplistic, and I am sure any academic
can come up with a much more sophisticated econometric model in order to try to
assess the need for office use in the future. However, the mere fact that it is
simple does not means that it is pointing into the wrong direction.
In fact this analysis fit
relatively well in the empirical evidence we have been gathering for years from
the market. The existing building environment for commercial office space is
sufficient in all the advanced economy. We do not need to build new space, but
need to improve the existing one to fit better standards. Local government will
have a significant responsibility as by granting building permits to build new
office space. If in parallel they do not act to remove the same amount of space
elsewhere, they are slowly but surely planting the seed for future vacancy. If
in doubt you can have a look at the Nederland, or certain cities in Eastern
Germany…
We have also argued in the past
that this trend should not necessarily be considered as a bad trend for listed
real estate company. Business models will surely need to adapt. Just being
there is likely not to be enough anymore. None of the existing office property
company anywhere in Europe has such a dominant market share, that it actually
needs a growing market in order to pursue it own growth. It is however very
likely that capital alone is not going to do the trick anymore. Emphasis is
going to move slowly but surely from capital to operation. Listed companies are
usually better prepared to face these challenges, than any other player in the
market. They usually integrate the full real estate value change and can
therefore identify change earlier than others and react faster.
The move is happening as we speak. As usual in
our industry it is happening slowly. Don’t be mistaken by the lack of wave on
the surface, this change is fundamental. I do not know whether or not Colliers is
right in estimating the numbers of sqm of office space that will be needed in
the future. However I do know that whoever will do my job in 2030, will be facing
a completely different industry. With hopefully a number of more professional
and bigger listed real estate companies.
Jul 22, 2011
What is wrong with rights?
ISS is one of the leading corporate governance solutions to the global financial community. Their home page claims that they want to “enable the financial community to manage the governance risk for the benefit of shareholders”. As part its governance approach ISS is currently conducting a review of its voting policies and have launched a public consultation available on their website (http://aox.ag/qI6t2v).
We have been engaging with ISS with regard to their voting policy in respect to shareholders approval of capital transaction excluding subscription rights. From that perspective we do strongly support Cohen & Steers view (for more information see our post “the good, the bad and the ugly, http://aox.ag/pcYyHI)
As a result of Cohen and Steers paper on the subject, ISS did take on board the subscription right issue; however, the way it is considered in the ISS document does raise eyebrows on the extent to which they have understood the topic.
On page 20 (question 33) of ISS questionnaire, the question is the following: What is an acceptable level of dilution for an issuance of equity without preemptive rights (for General Corporate Purposes)? (5%, 10%, 20%...).
Considering the little room for answer I thought it would be helpful to illustrate the way we are looking at the issue, and try to contribute to the debate.
I believe there are two perspectives that management has to take when looking at dilution concerns: The company perspective and the shareholder perspective. Let’s start with the easy one, the company view.
1 . Right. What right? (Please keep on reading before shouting at me)
The two important dilution factors that we do consider as management are, the NAV per share dilution/accretion, and the earnings per share dilution/accretion. None of these factors is influenced by the existence or not of preemption rights. The NAV/earning per share dilution or accretion is driven by the number of shares you issue as well as the price at which you issue them. Providing shareholders with rights or not is (on the face of it) irrelevant from the company view. What we will always try to do, is to issue the minimum numbers of new shares for the maximum possible proceeds. If we did not have to look at shareholders interest on top of the company interest, there is no argument that would make us consider preemptive rights. End of the story for the company side of life.
2- Don’t fight the market
If we will ever be in position to make a case for the preemptive rights it needs to be from the shareholder perspective.
In order to better understand why right could matter to shareholders let’s take a small example (I know this is not very academic, but I am not a teacher). Let assume a company that have one share, which market value of EUR 10. This company decides to double its share capital (so to issue another share) at a price of EUR 7.
The table below illustrates what would happen in the case of the existence of preemptive rights:

Table 1: Capital increase with subscription right.
As you can see, at the end of the transaction, the shareholder wealth have not changed (it is still equal to 10), and therefore he is deemed protected by the right. The new shareholders have paid EUR 8,5 for a share which is worth EUR 8,5. So far so good. Well not really. This reasoning is fundamentally flawed, and here is why.
Let’s take a look at the company perspective again. The management wants to issue the minimum numbers of shares (in this case one), AND maximize the proceeds. In the example above, there is someone who is ready to pay EUR 8,5 for the share, so there is no reason why the company would issue at a price below EUR 8,5.
Take this a step further. Someone is willing to pay EUR 8,5 for the new share, and the company wants to capture all the proceeds. Let’s see what happens to the wealth of the new and existing shareholder in this case (no subscription right is offered):

Table 2: Capital increase without subscription right.
The result is very bad for the old shareholder, which have lost EUR 0,75 of value in the process compared to the right issue. So it is true after all that rights do protect shareholders… Well again flawed reasoning.
If you look closely to the situation of the new shareholder, he actually got himself a EUR 0,75 free lunch in the transaction (on the back of the old shareholders). Shouldn’t we assume that someone out there is going to be willing to pay EUR 8,75 for the share and make only EUR 0,5 free lunch. And even then isn’t someone going to pay EUR 9 for the share and make only EUR 0,25 free lunch You can run the iteration, but eventually you are going to end up finding someone willing to pay EUR 10 for the shares. And if there is someone willing to pay EUR 10 for the share, then this is exactly the price at which the company is going to issue the shares. At EUR 10, the existing shareholders rights are worthless.
3- You would not do that would you?
Let’s consider the following transaction now. The same company decide to do the following: (i) pay a dividend of EUR 1,5 and then (ii) issue a new share at market (EUR 8,5 which is EUR 10 less the dividend). Here what the previous tables would look like:

Table 3: Dividend payment followed by capital increase
You will notice that the table 3 looks exactly the same than the table 1 above. It illustrates that the subscription right has the exact same effect then paying a dividend. It is basically a transfer of resource (and not wealth) between the company and its current shareholders. I am assuming that a lot of you would find it very odd to pay a dividend just before you raise new money (I know we just did that but we have no other choice as we are a REIT forced to pay by law). Well really offering a subscription right is economically the exact same think. If one does not make too much sense, why would the other do?
What I have tried to illustrate above is that in essence subscription rights do not provide shareholders with any kind of protection and do make a lot of sense PROVIDED that the shares at issued at their market price. This is usually the case when you offer the shares in an accelerated placement on the market in a book building process. Although in these processes the price achieved is usually lower than the screen price (the “infamous” discount) during the book building period the screen price is not very relevant. Considering the relative volumes of the market vs. the transaction, the screen does not drive the book. It is rather the book that drives the screen.
4- A solution that needs a problem
In all fairness to the subscription right, there is one instance where it is actually a very valuable feature to protect shareholders. This is usually when a capital increase is done at a given fix price (usually underwritten by a bank). This feature is usually used by issuers who are looking for a “certainty of funding” but cannot price the issue immediately. As much as issuer try to guess what the right price is (remember it wants to maximize proceeds) there is an almost certainty that the issue price is mispriced. Not the least because the bank underwriting the process is taking a “security margin” to avoid being stuck with the shares (another name of theses transaction is “deep discounted”). Being able to sell, or exercise its subscription rights does allow the shareholders to avoid offering a free lunch to a new subscriber. The obvious question that comes to mind is why would the issuer use such a process and not issue share overnight? Why does it take the risk to announce price weeks in advance, knowing that it is sub-optimizing its transaction? Any guess? Funnily enough the main reason why issuers do this is because of the subscription rights themselves. You need to give times to your shareholders to decide if they want to exercise them or not… In other words, if you do not have preemptive subscriptions rights, you will not need them either.
I am sure that I will have a number of strong discussions with some of alstria’s shareholders following this post. Although it has been drafted overnight, it is the result of long and intense discussions at alstria. Ever since we are public, we have tried to understand the preemptive right concept. So far we were unable to find any instance were the preemptive rights added value. We have in fact refused to use the deep discounted process while advisors where arguing that “it does not matter for your shareholders as they can use their rights”. It may be that we are biased. Considering the sensitivity and importance of the subject, I am this time more than for any of our other blog post, happy to open the floor to public or private comments.
Olivier
Apr 4, 2011
Apr 1, 2011
The good, the bad and the ugly
 In a recent paper, signed by Joseph Harvey, President and CIO of Cohen and Steers (disclaimer, Cohen and Steers is as far as I know one of our shareholder), the investment manager argues about the merits of allowing European REIT to execute capital increase excluding subscription rights. (The document can be read at the following address http://bit.ly/flBlrP)
Dec 9, 2010
Japanese’s whispers
I have put on a paper some thoughts while I was in roadshow in Asia, following meeting with investors and investment analysts. As a disclaimer, I am writing this in the middle of a jetlagged night, and I clearly do not pretend to know what I am talking about here.

1- In China, it seems that it is more reasonable to invest into less known secondary cities, than in the majors. Rational being that a lot of speculation is driven by some cities names, not by economics. Ring a bell in Germany as well. Except that Frankfurt is by no way a major city by Chinese standards

Nov 24, 2010
Aug 18, 2010
Honi soit qui mal y pense

In the foreword to a green supplement in the magazine House and Garden (in 2008), the Prince wrote: "Why, I must ask, does being 'green' mean building with glass and steel and concrete and then adding wind turbines, solar panels, water heaters, sedum roofs, glass atria - all the paraphernalia of a new 'green building industry' - to offset buildings that are inefficient in the first place?
"That many of these add-ons are mere gestures, at best, is now clear, as their impacts on home energy consumption can now be measured and usually offer scant justification for the radical nature of the design." (see http://bit.ly/bjibZy for more on this)
Jul 8, 2010
We (almost) made it happen

May 18, 2009
Evolution

Real Estate Investment Trust or REIT, is a global trademark which started in the US in the 1960’s, and is now spread across the globe. When a company define itself as a REIT, it mean that it adhere to a number of simple concept. Its is usually a listed company, its business must be real estate investment it is tax transparent, and it pays most of its profit as dividend. Although the local legislation differs here and there, those are the main characteristic of REIT worldwide.
May 14, 2009
Flat Lines

The new value of the IPD/alstria DMX index which measures the reversion potential of German office rents shows for the second consecutive year that, on average, there is little reversion to be expected in the German rental market. (Full IPD study and result can be found here).
This does not come as a surprise to me and hopefully will not surprise any of the investors we are used to speak to, as this is one of the base case assumptions we have been working on since inception.
Apr 28, 2009
Qui va piano va sano

A few weeks ago, following our annual press conference, we got this interesting question from a real estate equity sales desk: “I have one particular question on current disposal talks. If pricing is not very much of an issue and the buyers are mostly equity buyers and have little constraints regarding the debt financing, what is currently holding up the process?”
Apr 17, 2009
Apples and bananas
For real estate listed companies like for other industries, March was the month of FY08 earning season and we did publish our numbers on the 31st of March (a replay of the webcast of alstria result presentation can be found here).
Mar 5, 2009
In the credit crunch, the credit might have already left, but the crunch still has to come
In November 2008 a panelist at the ninth annual European Real Estate Opportunity & Private Fund Investing Forum had the following remark: “Is CMBS dead? It can't be dead--there's no other place to get [that money] from” I guess it is relatively fair to say that if CMBS is not clinically dead, it is in a very deep coma.
European real estate markets were less relying on the CMBS market than the US markets. Nevertheless the share of the CMBS market has been constantly growing and it is estimated that more than 20% of the commercial real estate financing was financed through these markets. That still leaves us with a significant number of billions of commercial real estate financed in the CMBS markets…
European real estate markets were less relying on the CMBS market than the US markets. Nevertheless the share of the CMBS market has been constantly growing and it is estimated that more than 20% of the commercial real estate financing was financed through these markets. That still leaves us with a significant number of billions of commercial real estate financed in the CMBS markets…
Subscribe to:
Posts (Atom)